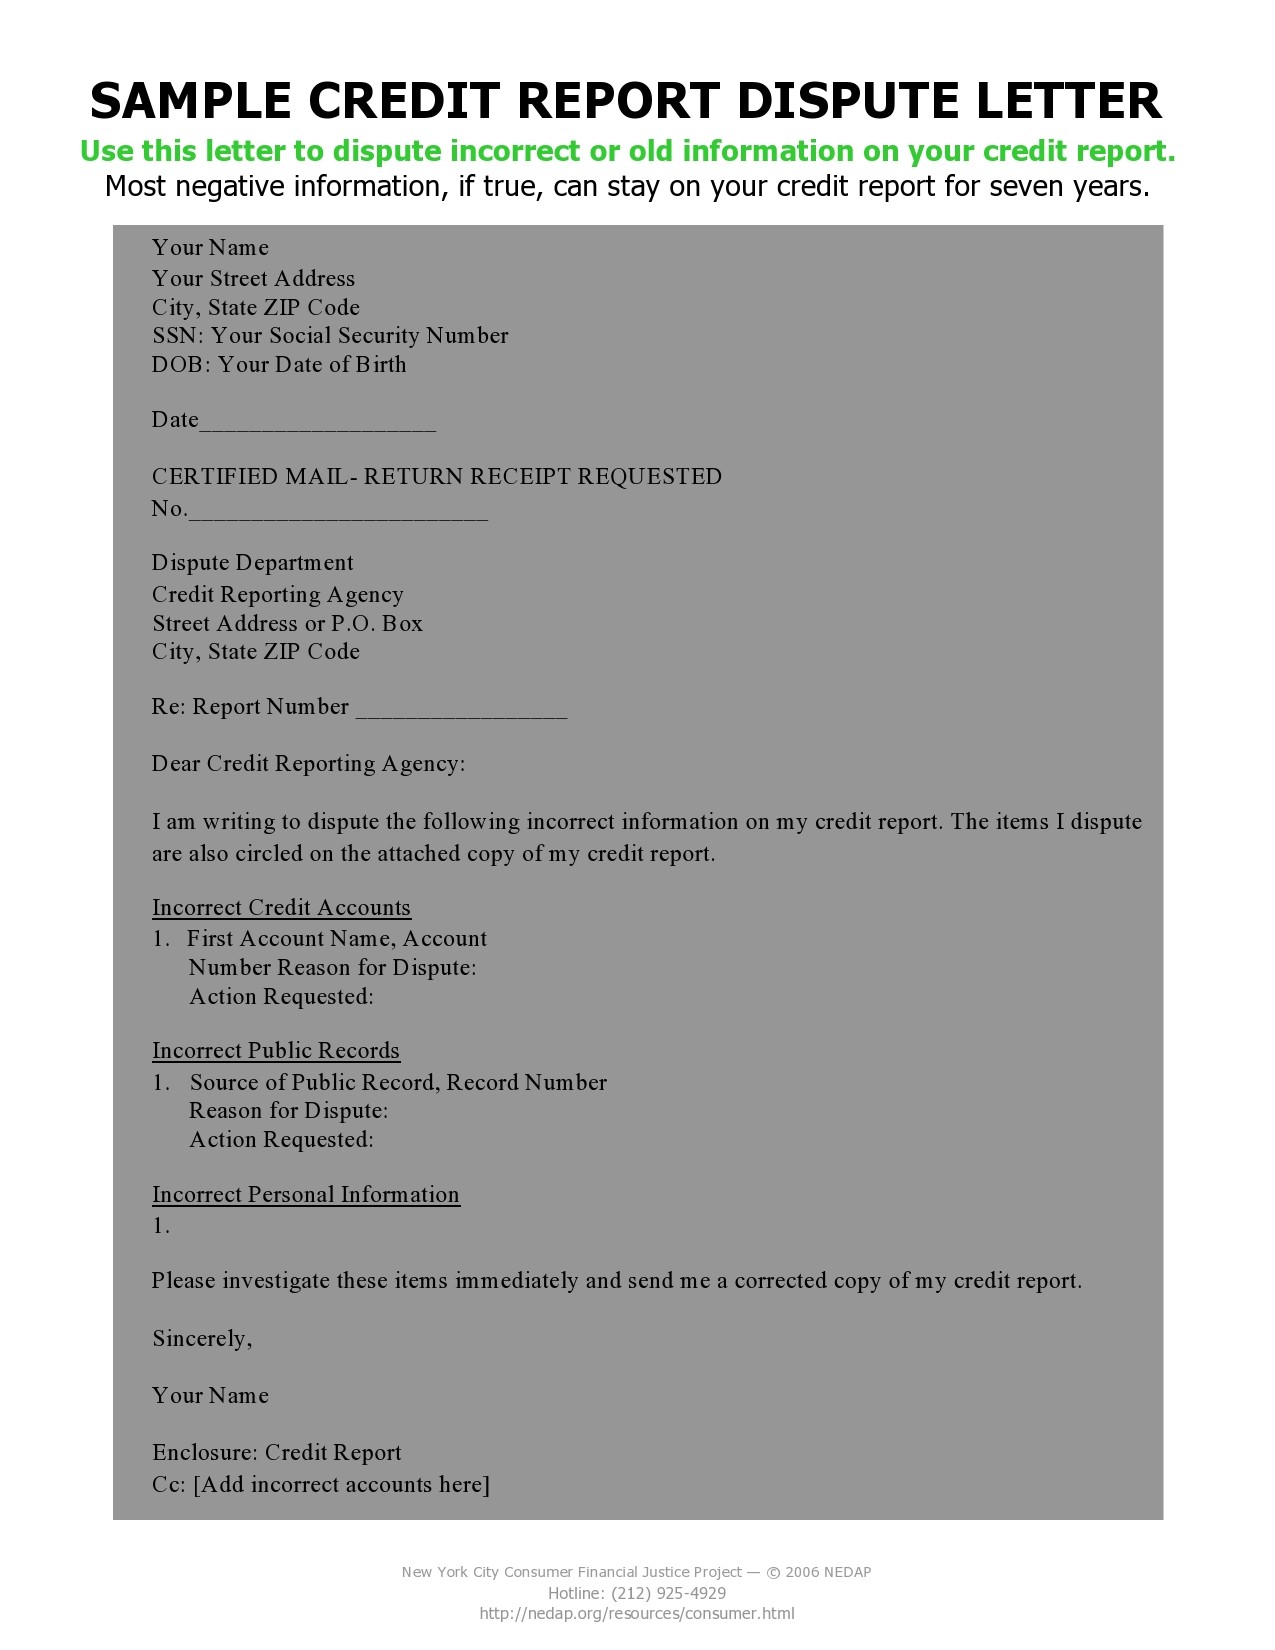
Credit Report Dispute Letter Template serves as your passport to correcting mistakes that could be silently draining your financial future, and in the bustling rhythm of Asian-inspired diligence, a well‑crafted letter can restore balance to your credit narrative. Whether you are a recent college graduate navigating student loans, a small‑business owner expanding across borders, or a seasoned professional planning for retirement, the power of a precise dispute letter cannot be overstated. This article walks you through every nuance of the template, from the essential components that echo respect and clarity to actionable steps that guarantee your request is taken seriously by credit bureaus and lenders alike.
Why Disputing Credit Report Errors Matters
In many Asian cultures, reputation and harmony are prized above all, and a credit report is the modern reflection of that personal reputation in the financial arena. An error—be it a misspelled name, an outdated address, or a phantom delinquency—can ripple through loan applications, rental agreements, and even employment opportunities. By taking the time to dispute inaccuracies, you protect not only your numerical score but also the trust you have cultivated with banks, landlords, and business partners.
Impact on Credit Score
A single erroneous late payment can shave dozens of points off a credit score, potentially moving you from “excellent” to “good” or even “fair.” This shift can increase interest rates on mortgages, car loans, and credit cards, costing you thousands over the life of a loan. Moreover, many lenders use automated underwriting systems that flag any negative mark, no matter how old or inaccurate, causing delays or outright denials.
Legal Rights Under Consumer Protection Laws
In the United States, the Fair Credit Reporting Act (FCRA) empowers consumers to request investigations into disputed items. The law obliges credit bureaus to respond within 30 days, correct verified errors, and provide a free copy of the revised report. Understanding these rights helps you frame your dispute letter with confidence, knowing that the bureau is legally bound to act.
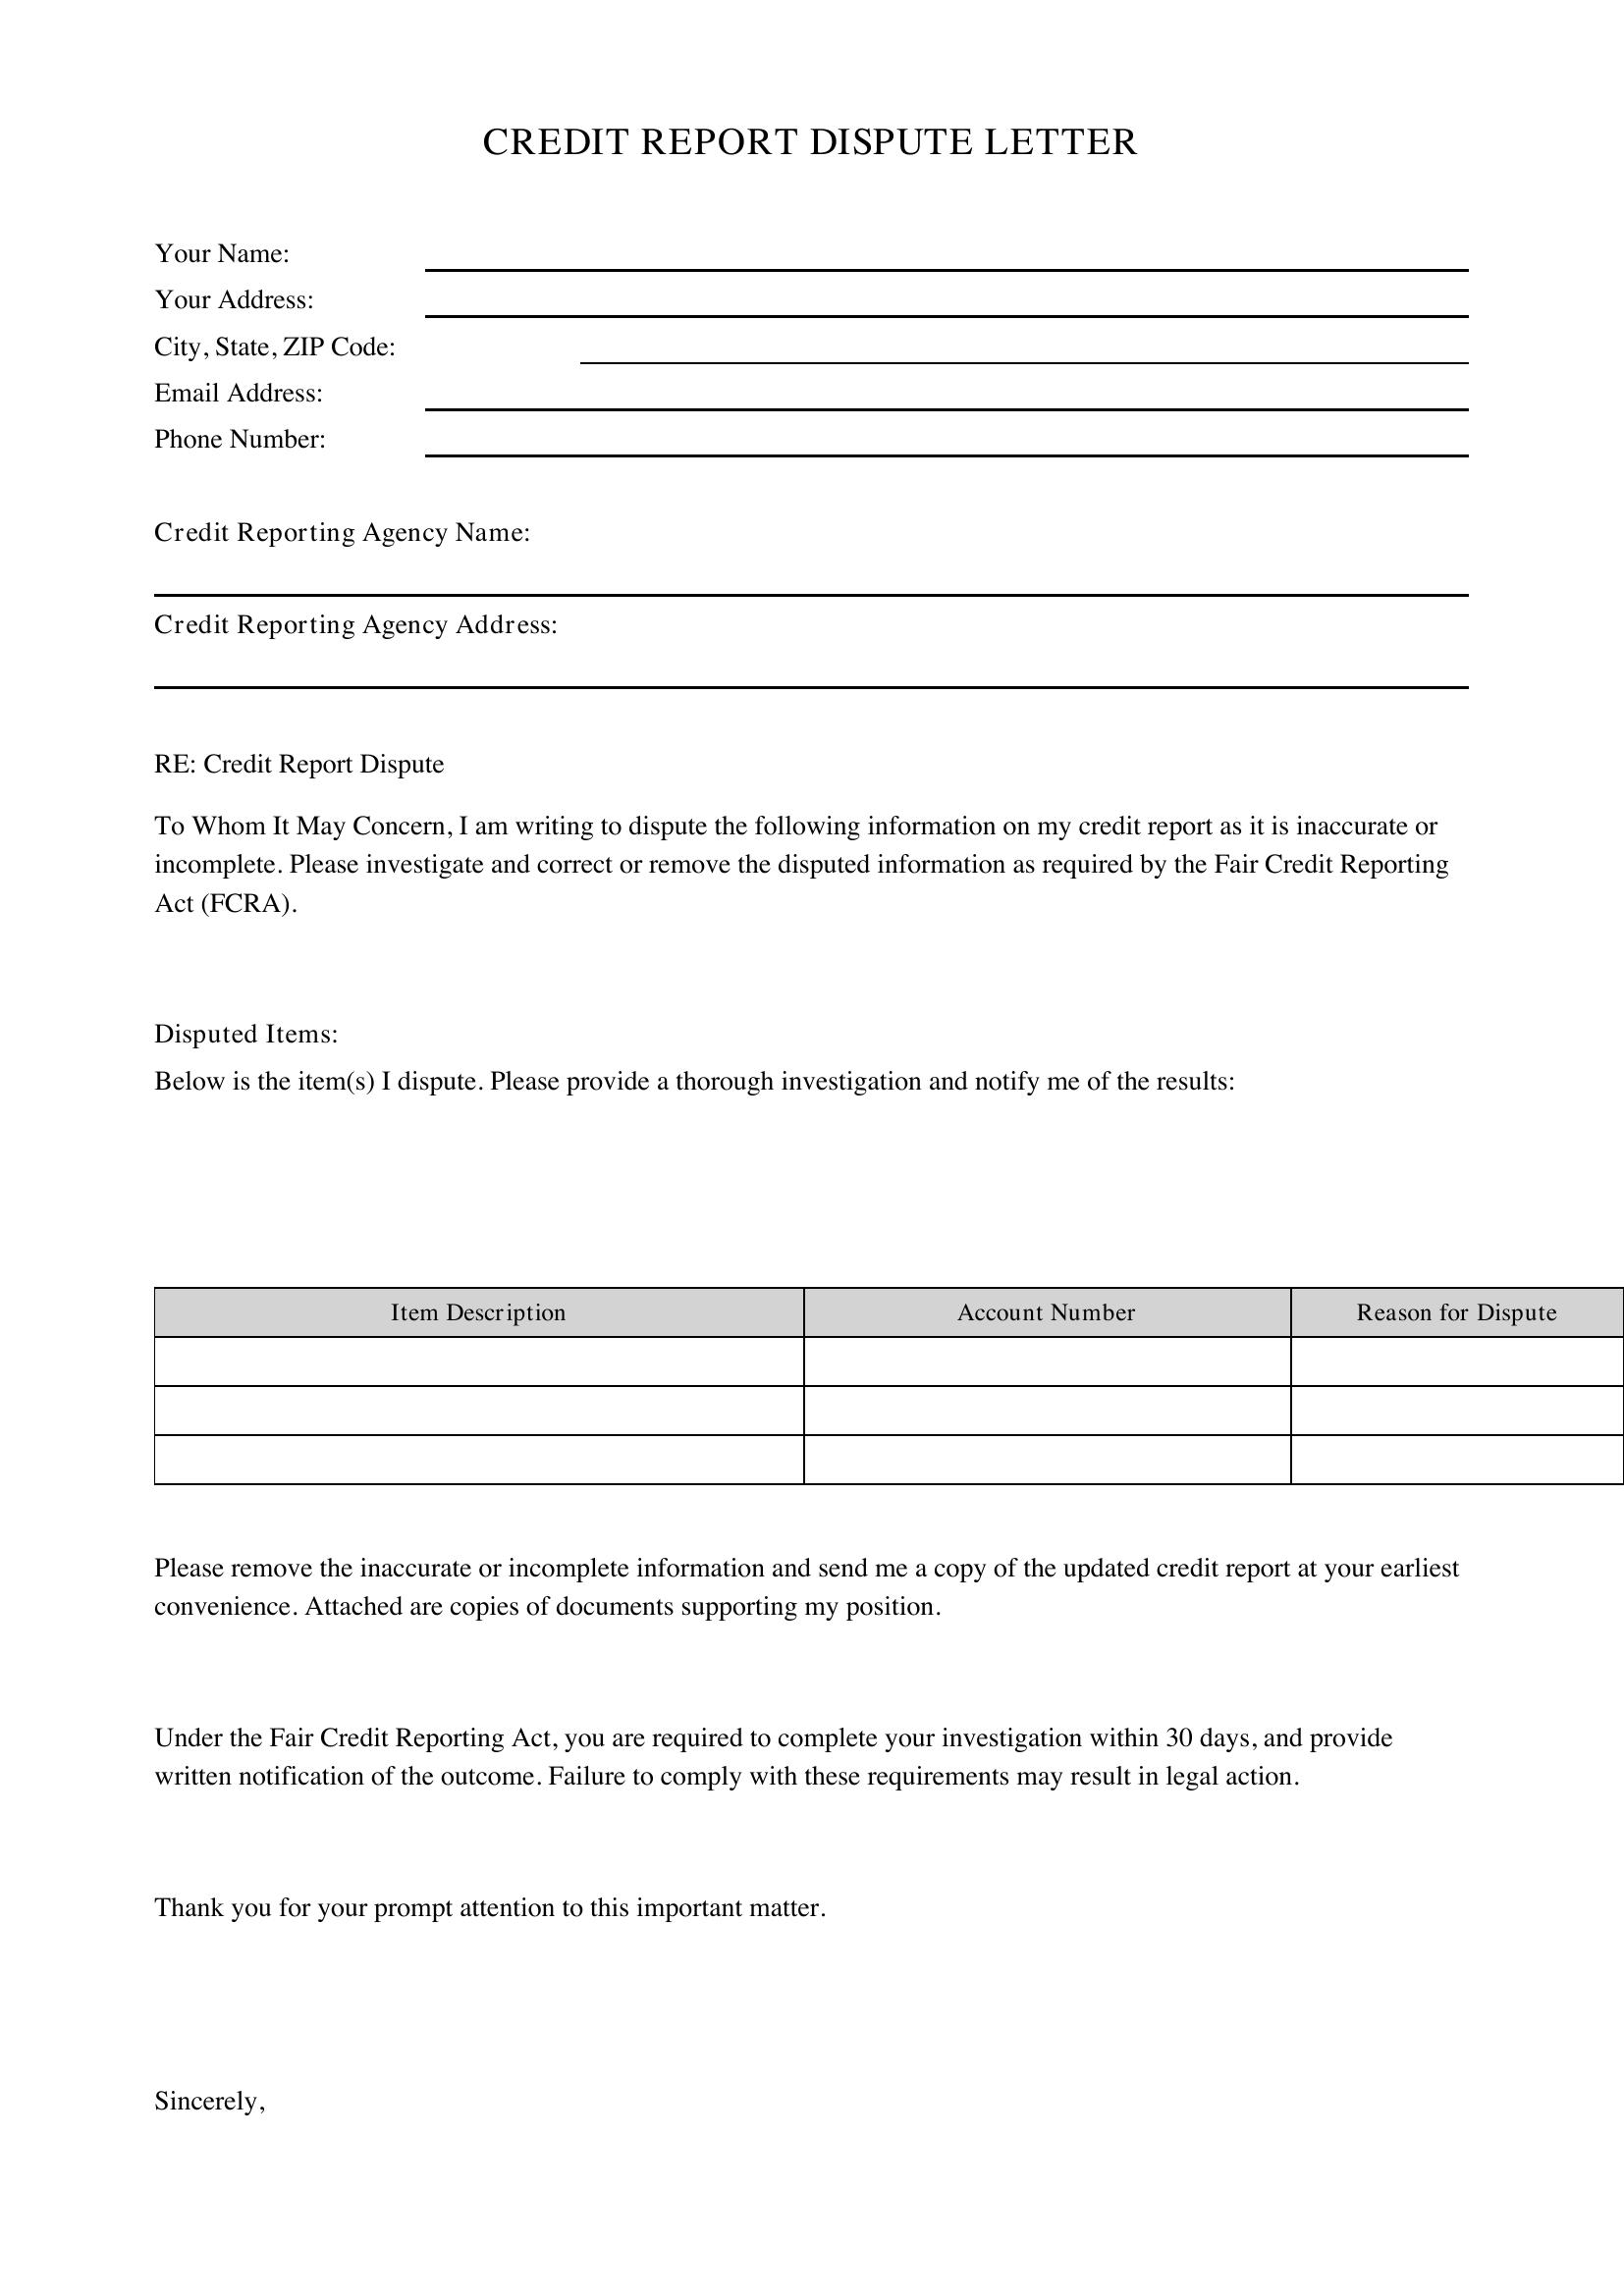
Key Components of an Effective Credit Report Dispute Letter Template
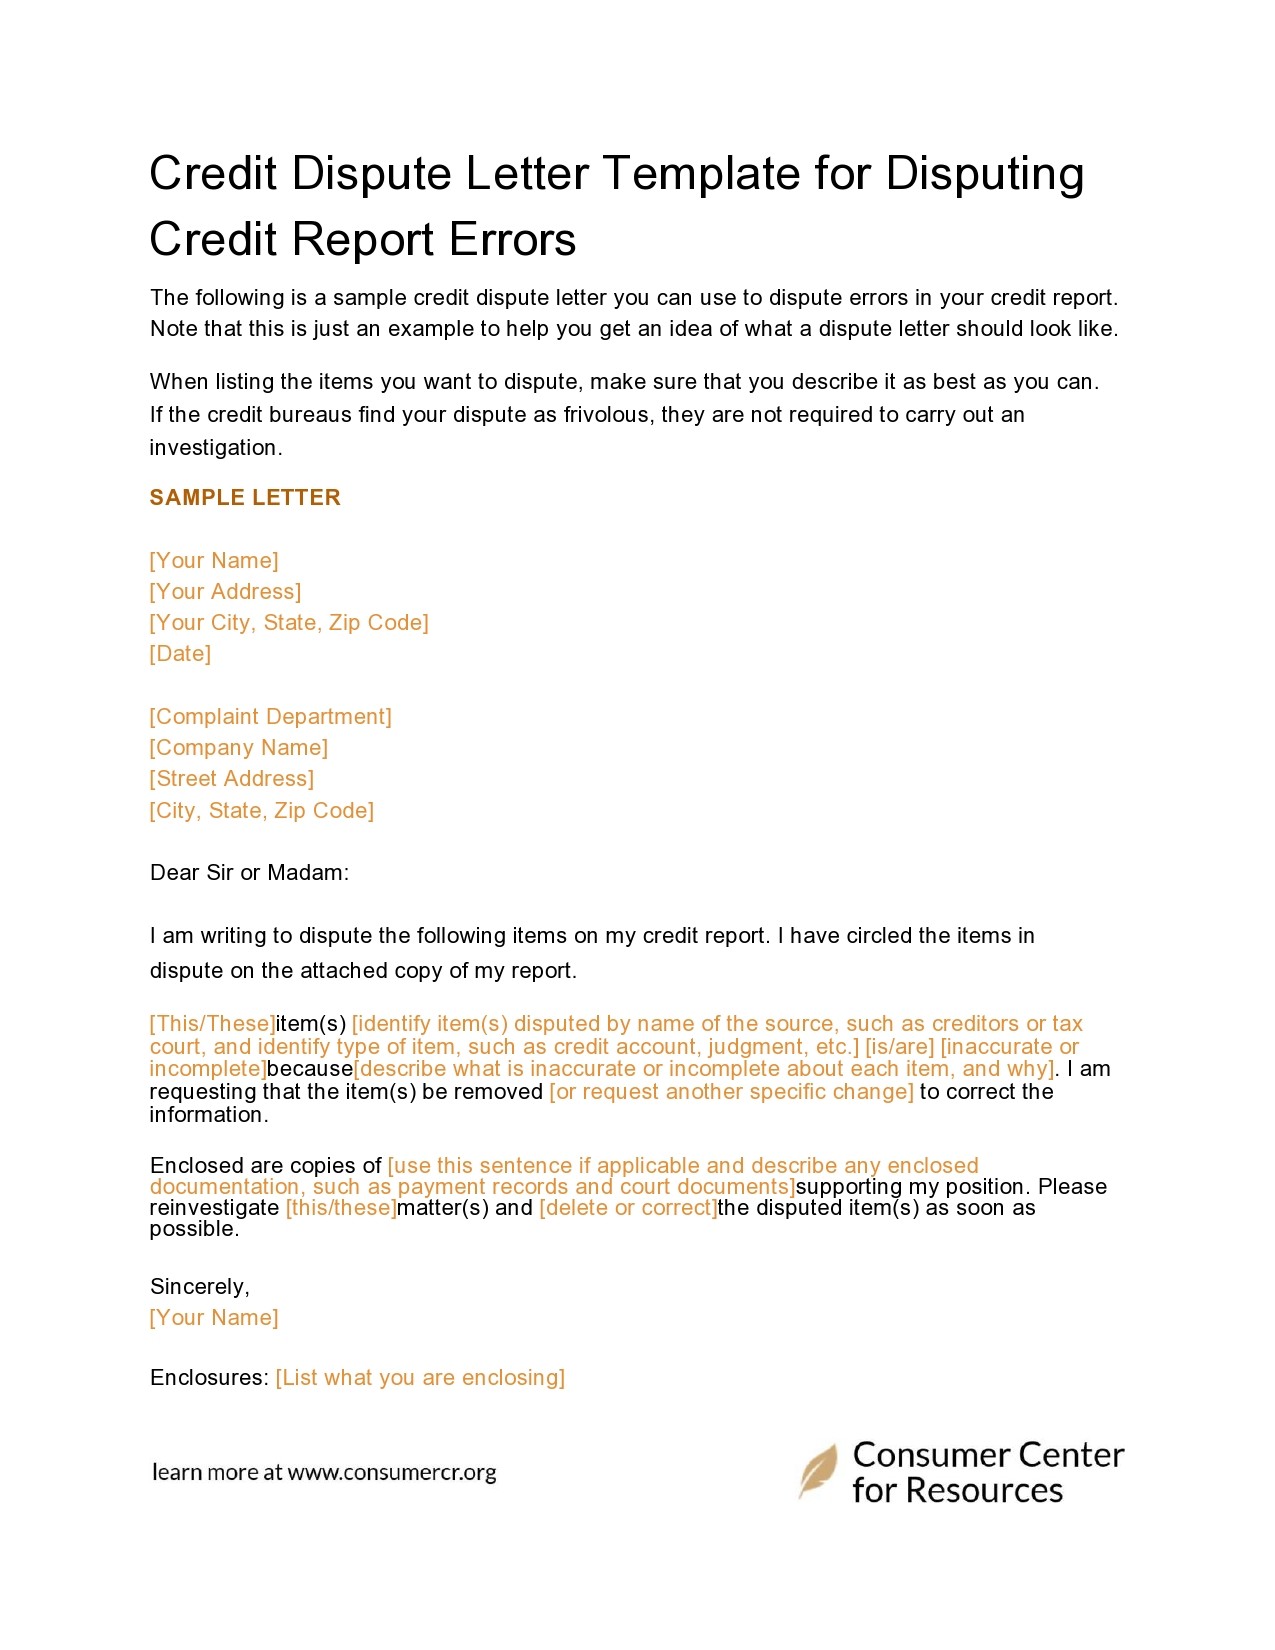
Just as a well‑balanced bowl of rice and vegetables satisfies both palate and nutrition, a dispute letter must balance formality, specificity, and supporting evidence. Below are the critical sections you should never omit.
Header and Personal Information
Begin with your full legal name, current mailing address, phone number, and email. Place the date directly beneath this information. This block mirrors the courteous introduction you would give in a business meeting, establishing identity and contact channels right away.
Account Identification
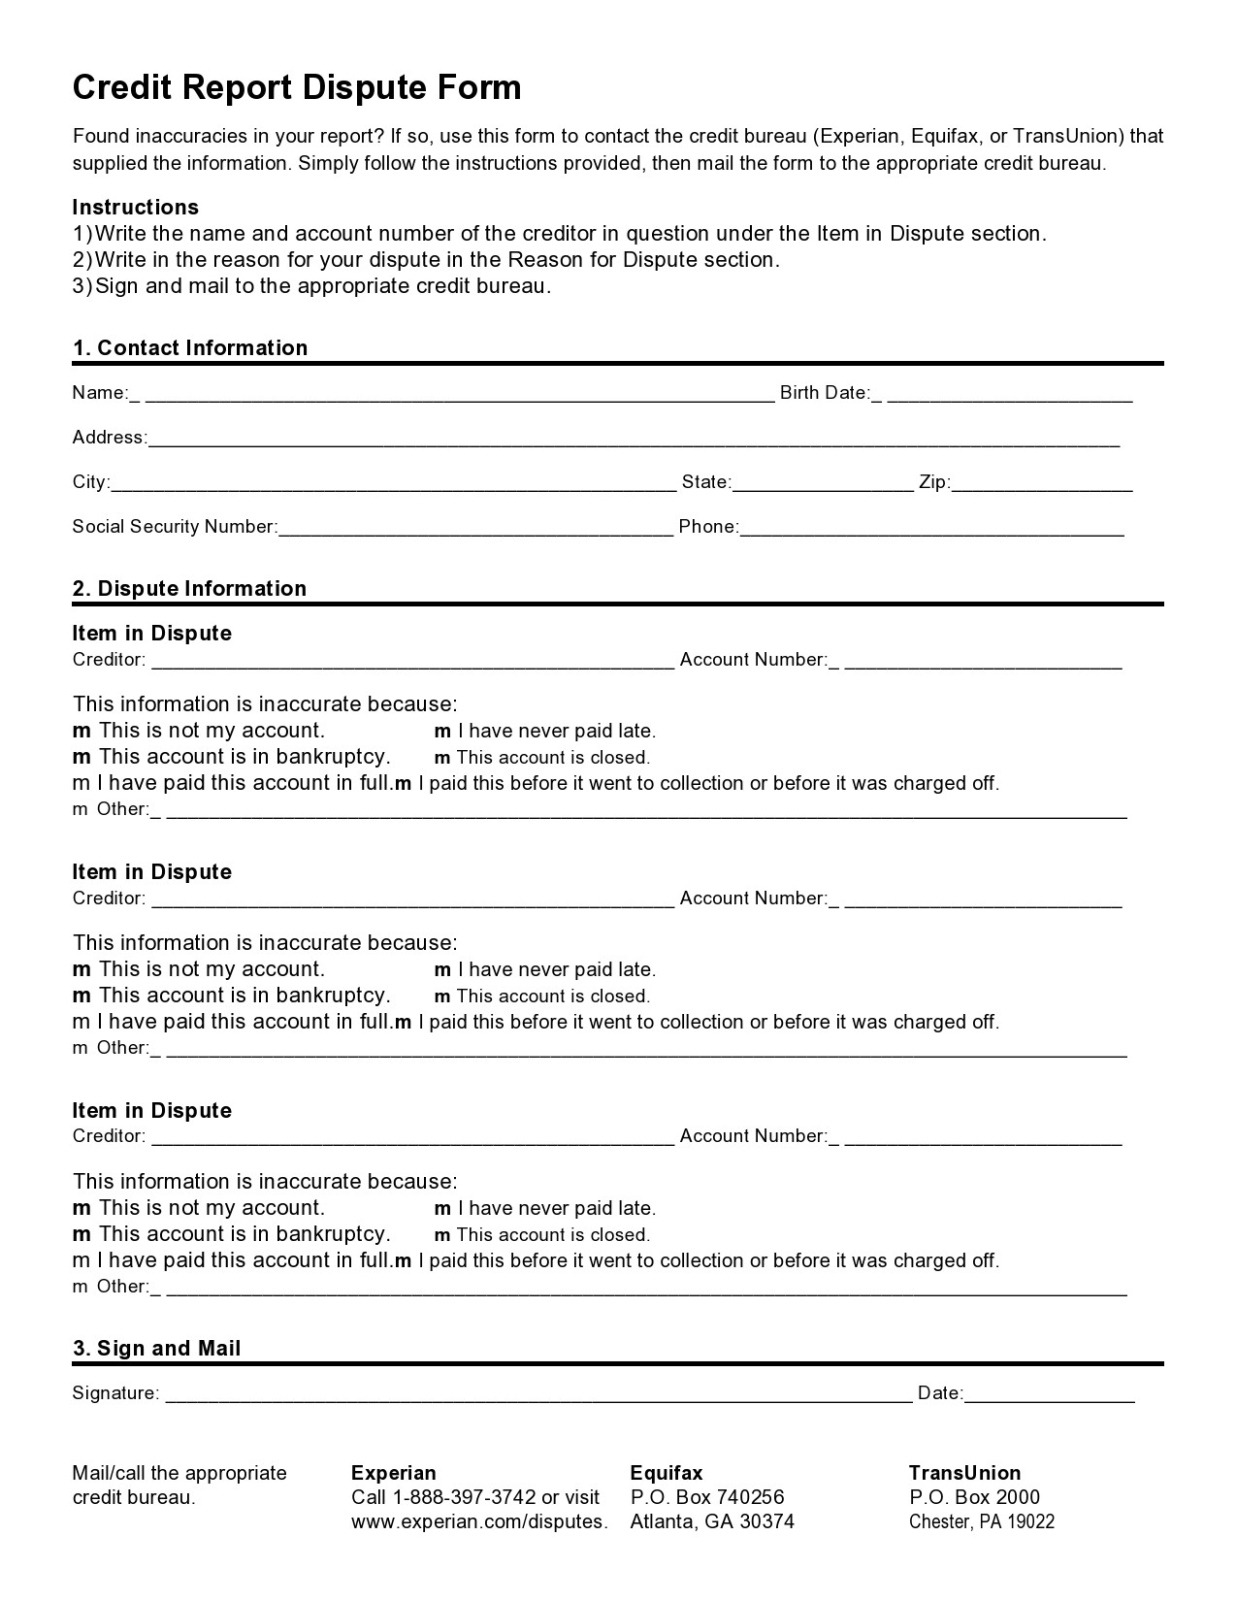
Clearly list each disputed account using the creditor’s name, account number, and the exact line item as it appears on your credit report. If you are disputing multiple items, number them for easy reference. Precision here prevents any ambiguity that could stall the investigation.
Precise Description of Dispute
State, in plain language, why the item is inaccurate. Include dates, amounts, and any discrepancies you have identified. For example, “The account shows a $500 charge on 03/15/2022 that I never authorized.” The more specific you are, the easier it is for the bureau to locate the record and verify your claim.
Supporting Documentation
Attach copies—not originals—of relevant documents: bank statements, payment receipts, settlement letters, or correspondence with the creditor. Label each attachment clearly (e.g., “Attachment A – Payment Receipt”). In Asian business etiquette, providing evidence demonstrates respect for the recipient’s time and diligence.
Request for Action and Closing
Conclude with a courteous yet firm request: “Please investigate this matter and delete the inaccurate entry from my credit report within the statutory 30‑day period.” End with a polite sign‑off, your signature, and a typed name for readability.
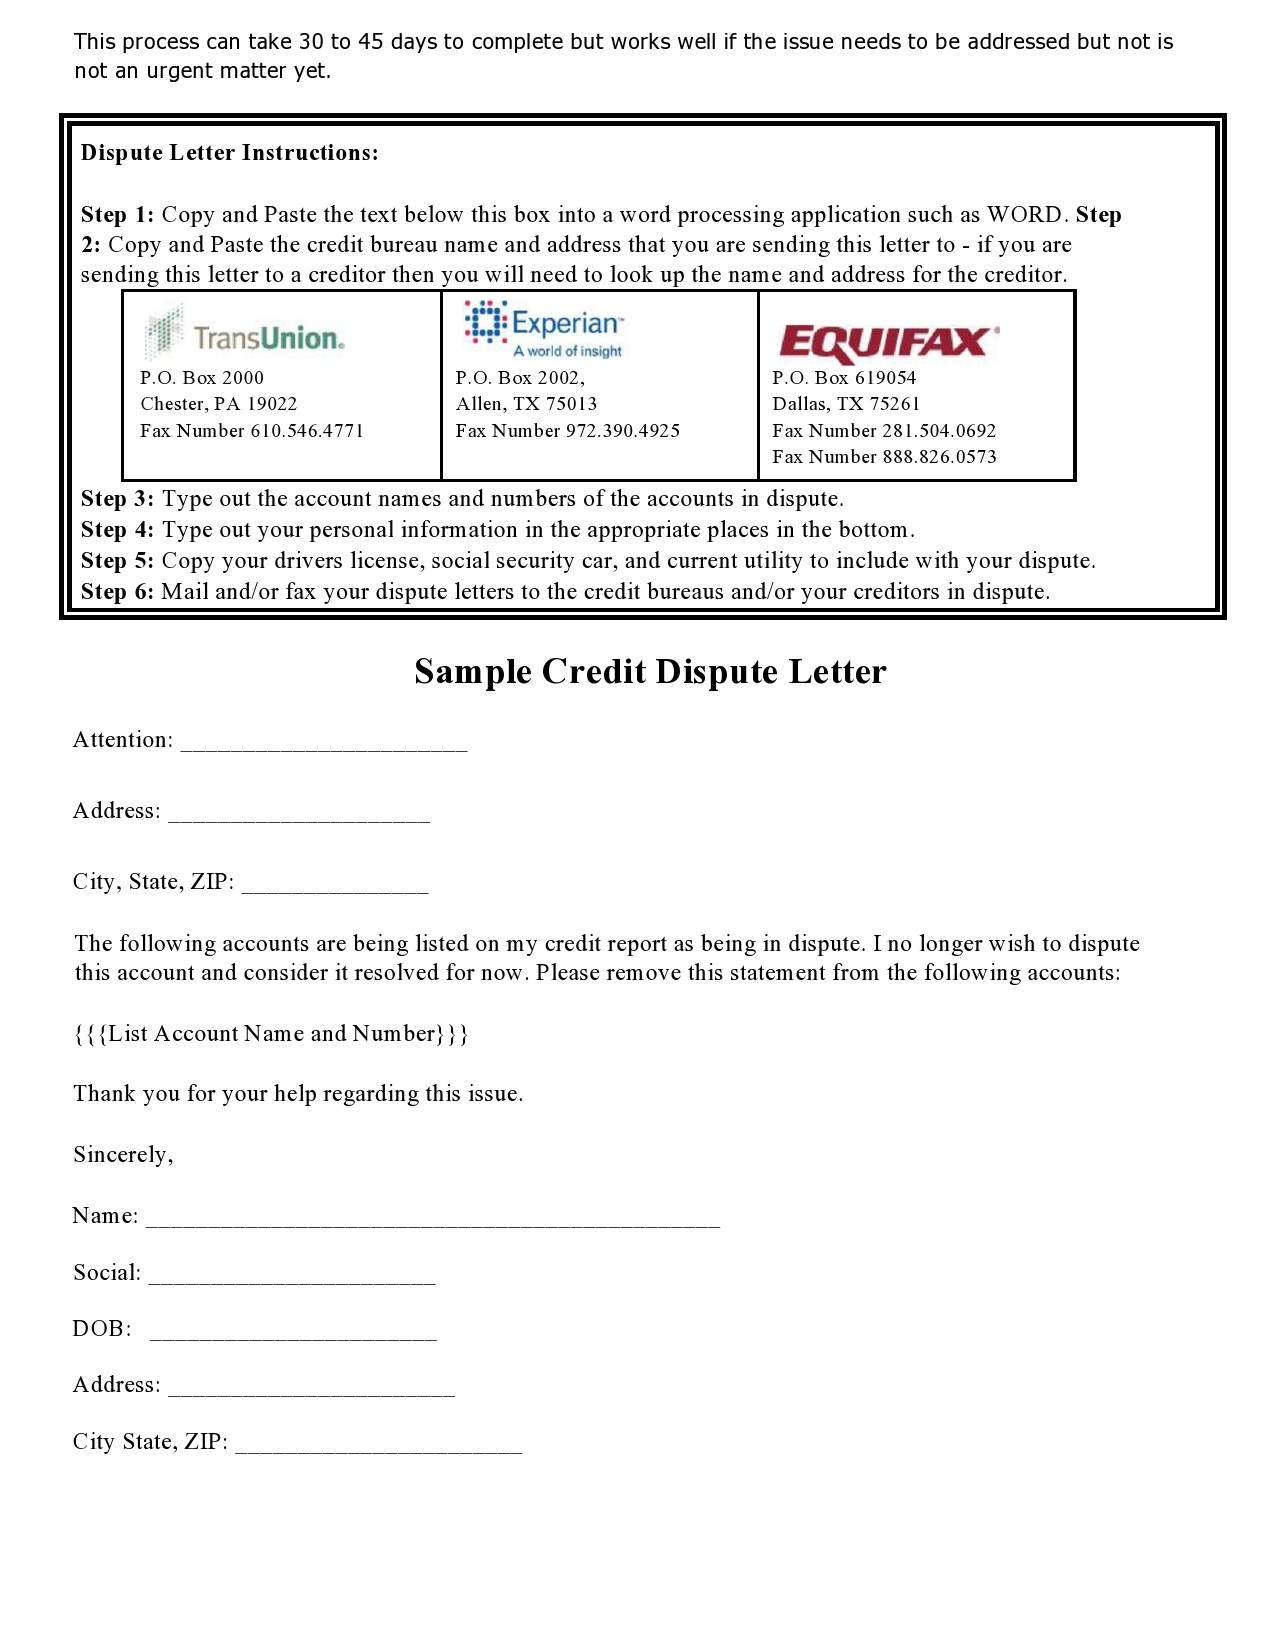
Step‑by‑Step Guide to Filling Out the Template
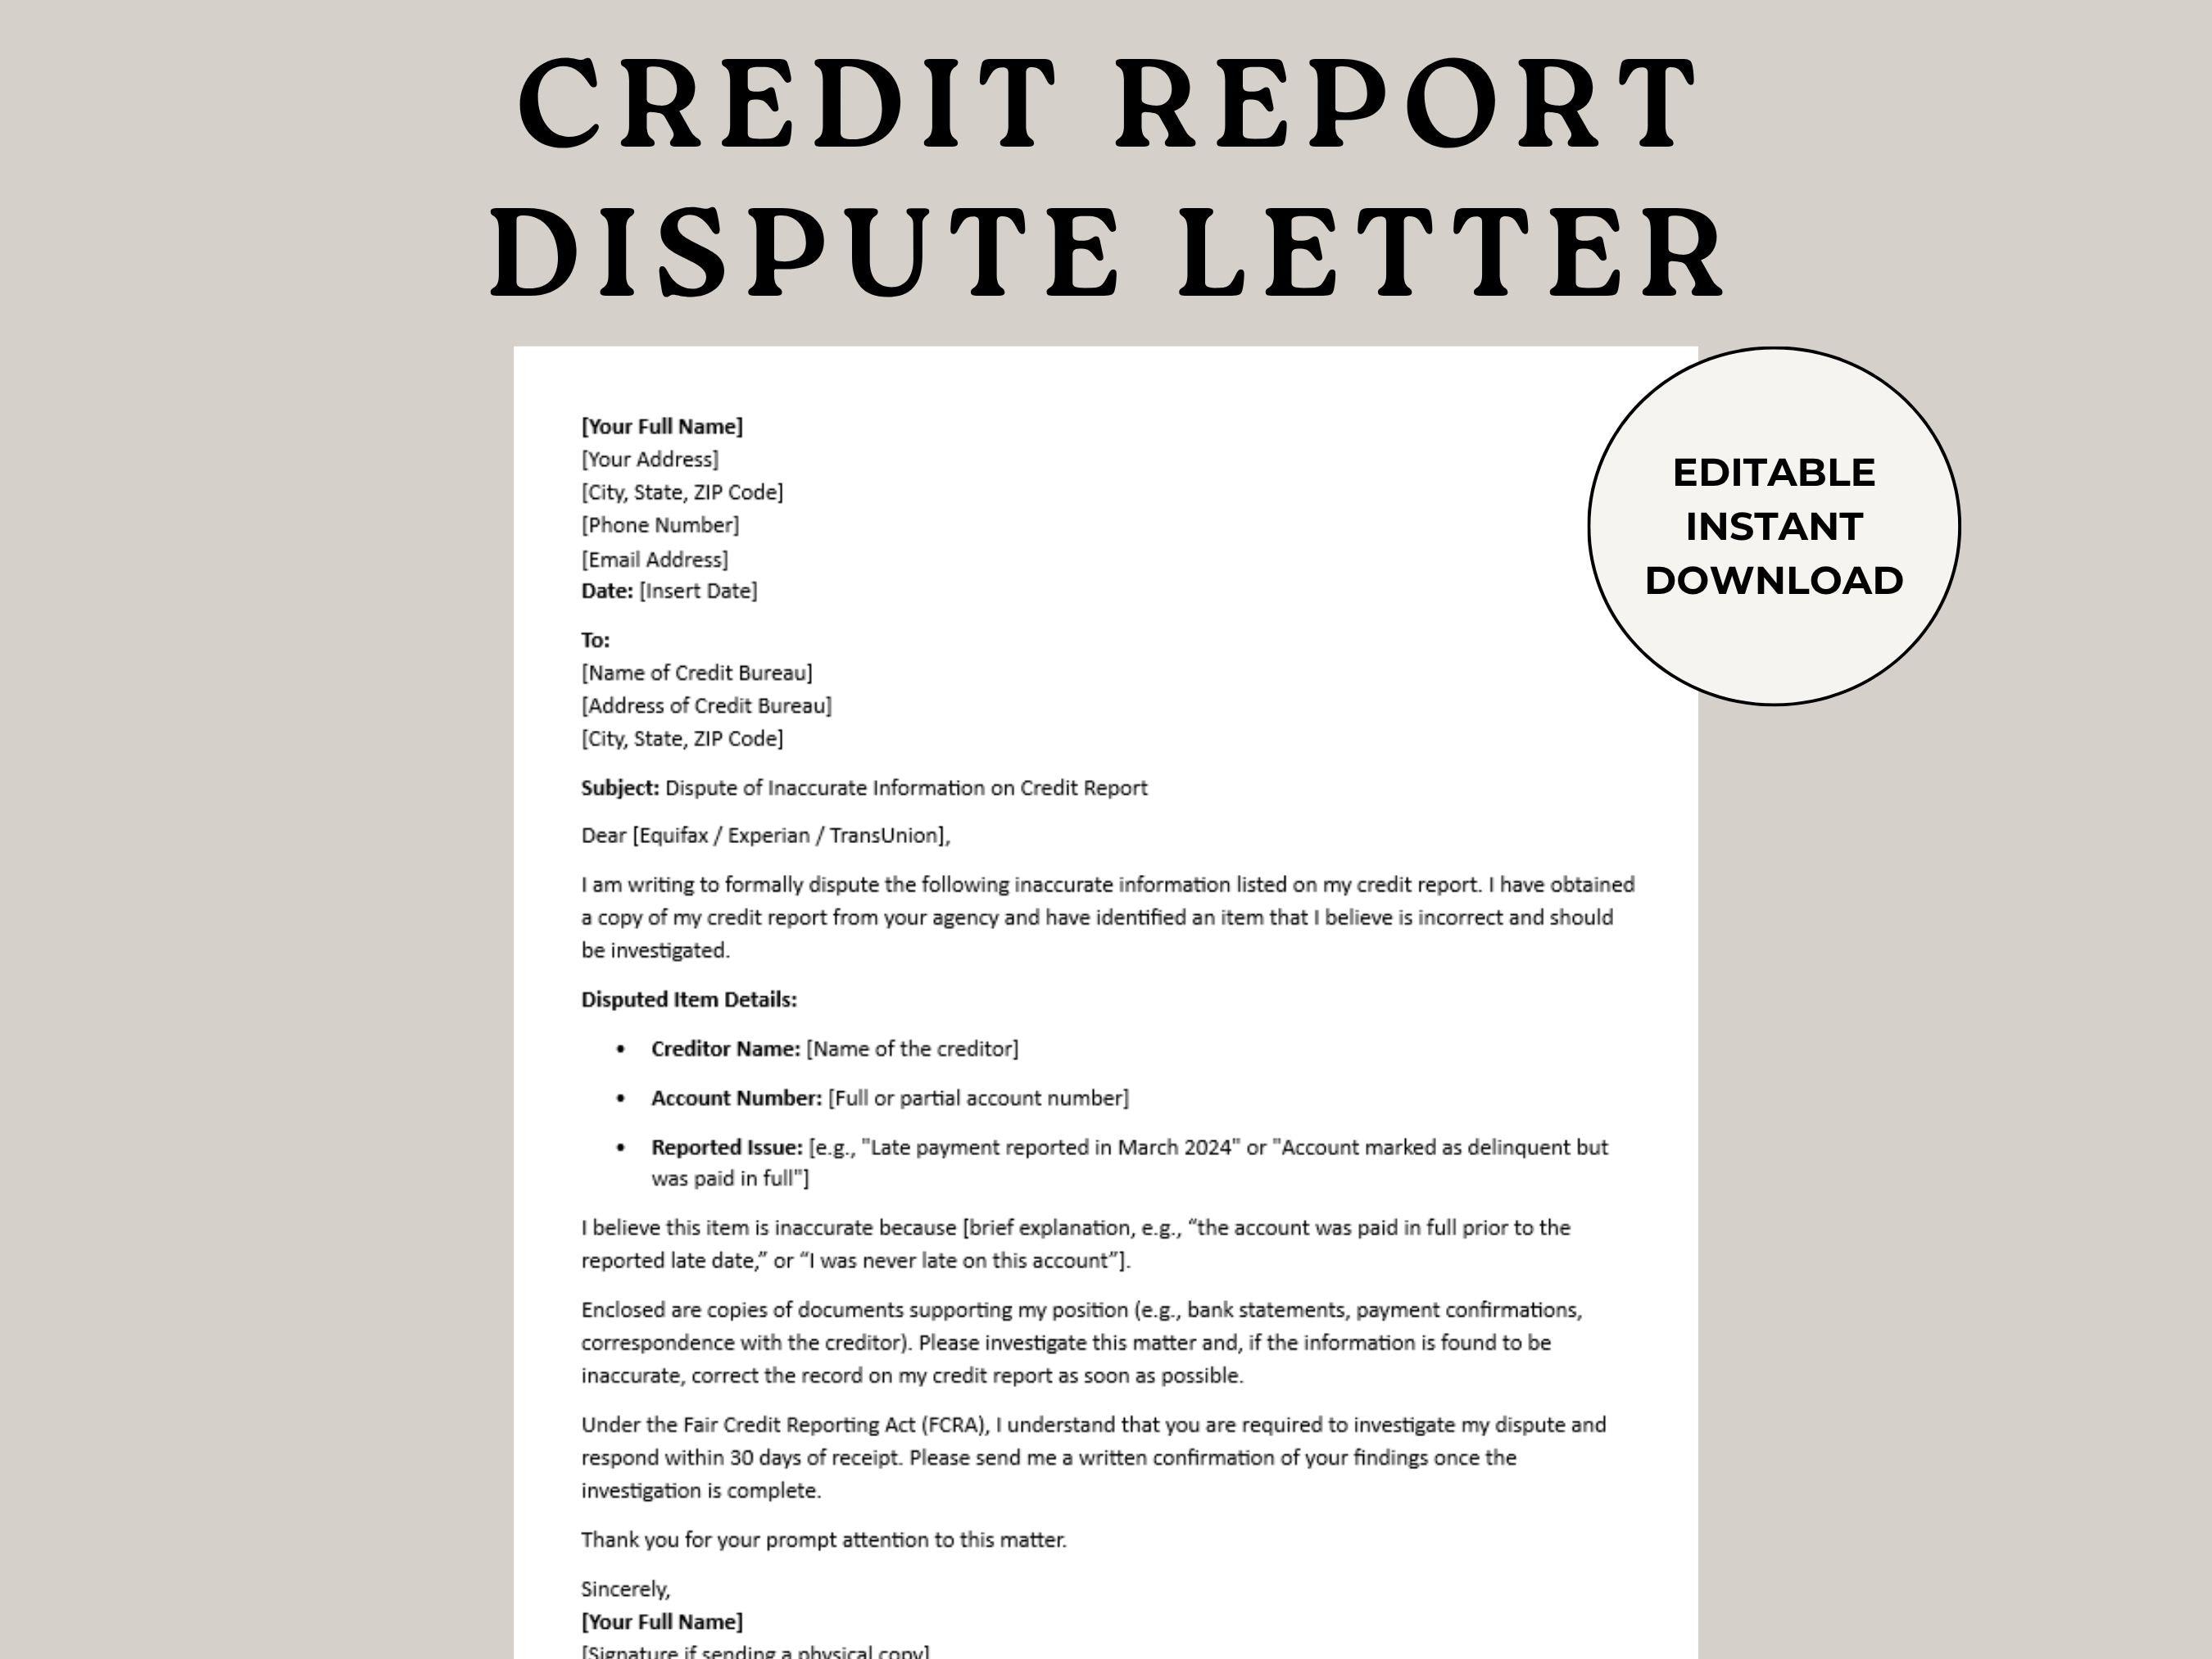
Transforming a blank template into a persuasive letter is a systematic process. Follow these steps to ensure completeness and professionalism.
Gather Your Credit Report
Obtain a recent copy of your credit report from each of the three major bureaus—Equifax, Experian, and TransUnion. Review the reports side by side, marking every line that appears questionable. Having all reports in front of you prevents oversight and allows you to spot discrepancies that appear in only one bureau.
Identify Inaccurate Items
For each item, write down the exact wording, date, and amount as it appears. Then, compare it with your own records (payment logs, loan agreements, etc.). Highlight any mismatches, such as a “charged‑off” status that you actually settled, or an “inquiry” you never authorized.
Draft the Letter Using the Template
Plug the gathered information into the appropriate sections of the template. Keep sentences concise, avoid jargon, and maintain a respectful tone. Remember that the letter will likely be read by a compliance officer, so clarity is paramount.
Attach Evidence
Arrange your supporting documents in the order referenced in the letter. Use a paperclip or a simple folder if mailing physically; for electronic submissions, merge the PDFs in the same sequence. Label each attachment within the letter (“see Attachment B”) so the reviewer can cross‑reference instantly.
Send via Certified Mail or Secure Portal
Certified mail with return receipt provides proof of delivery, a practice favored in many Asian business cultures for its traceability. If the bureau offers a secure online portal, upload the same documents there and keep a screenshot of the confirmation page. Either method ensures you have a verifiable record of your submission.
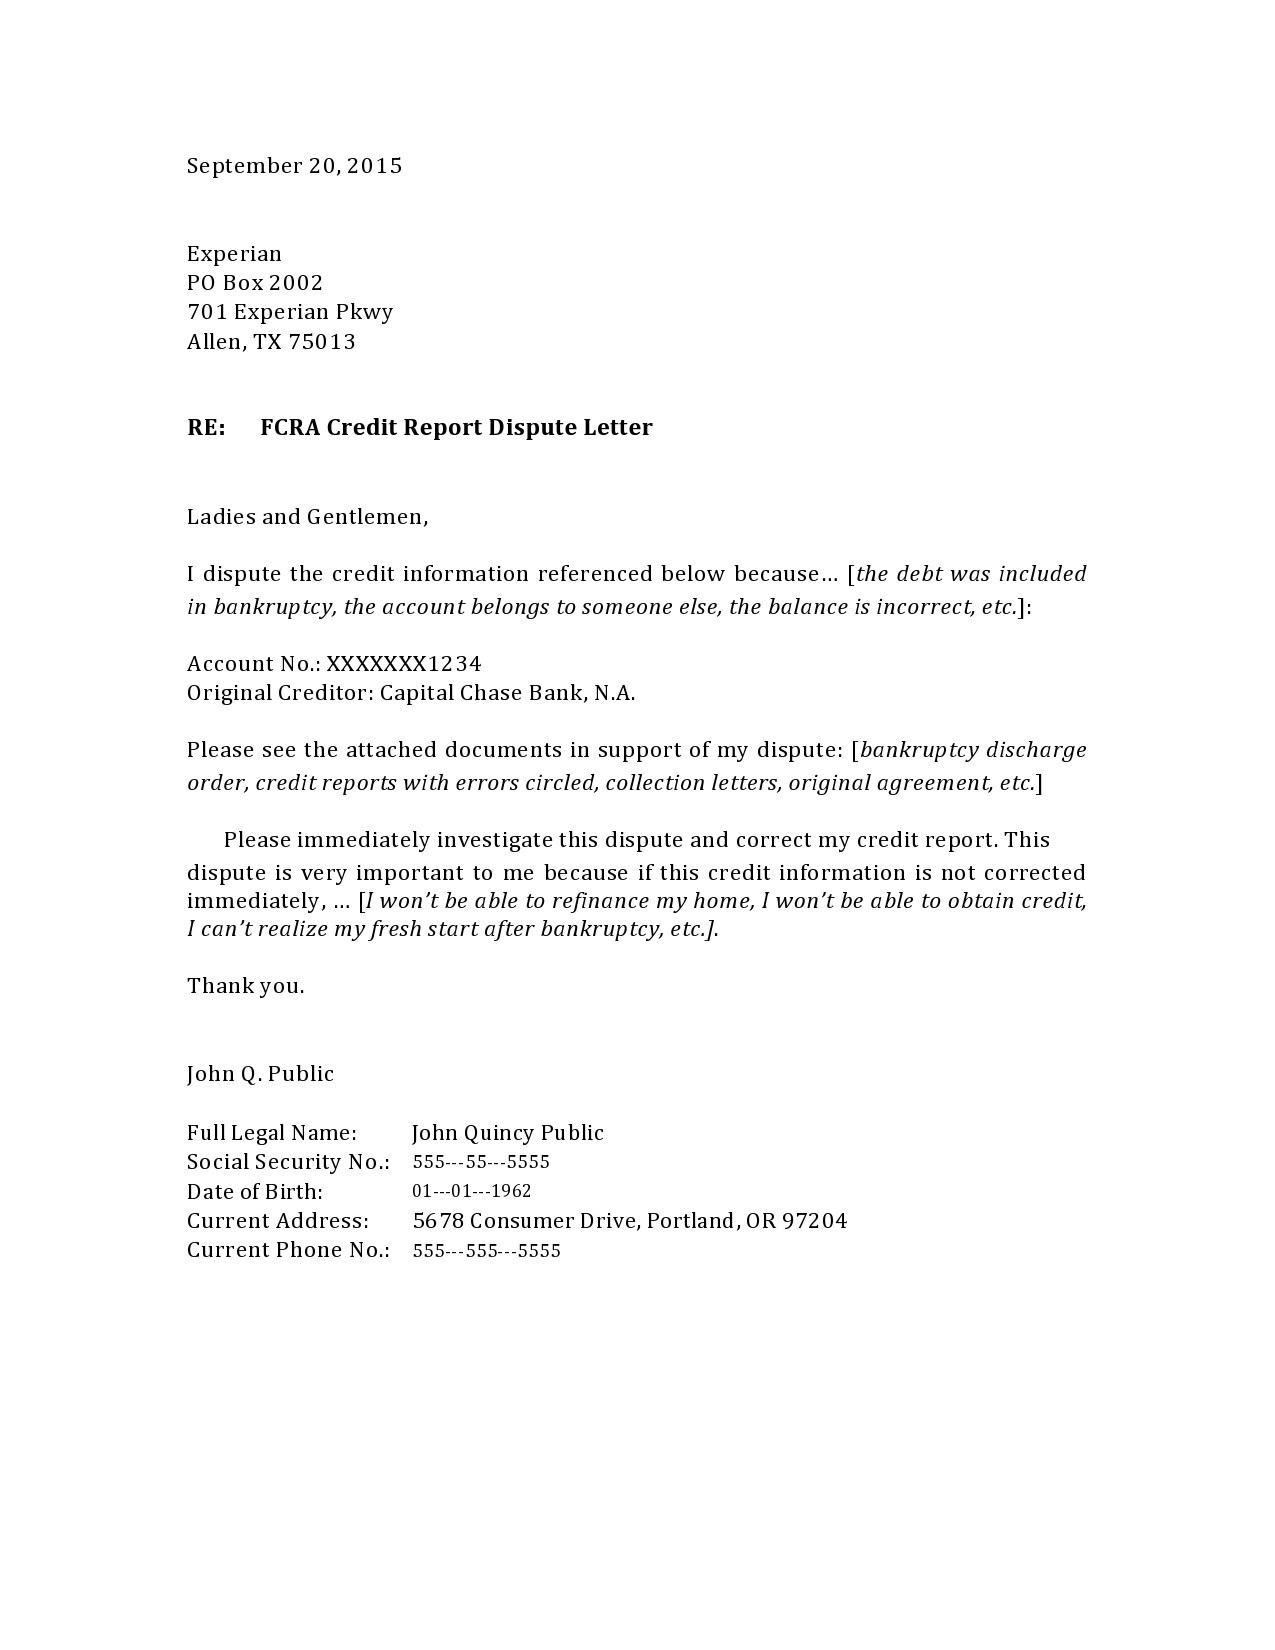
Sample Credit Report Dispute Letter – Real‑World Example
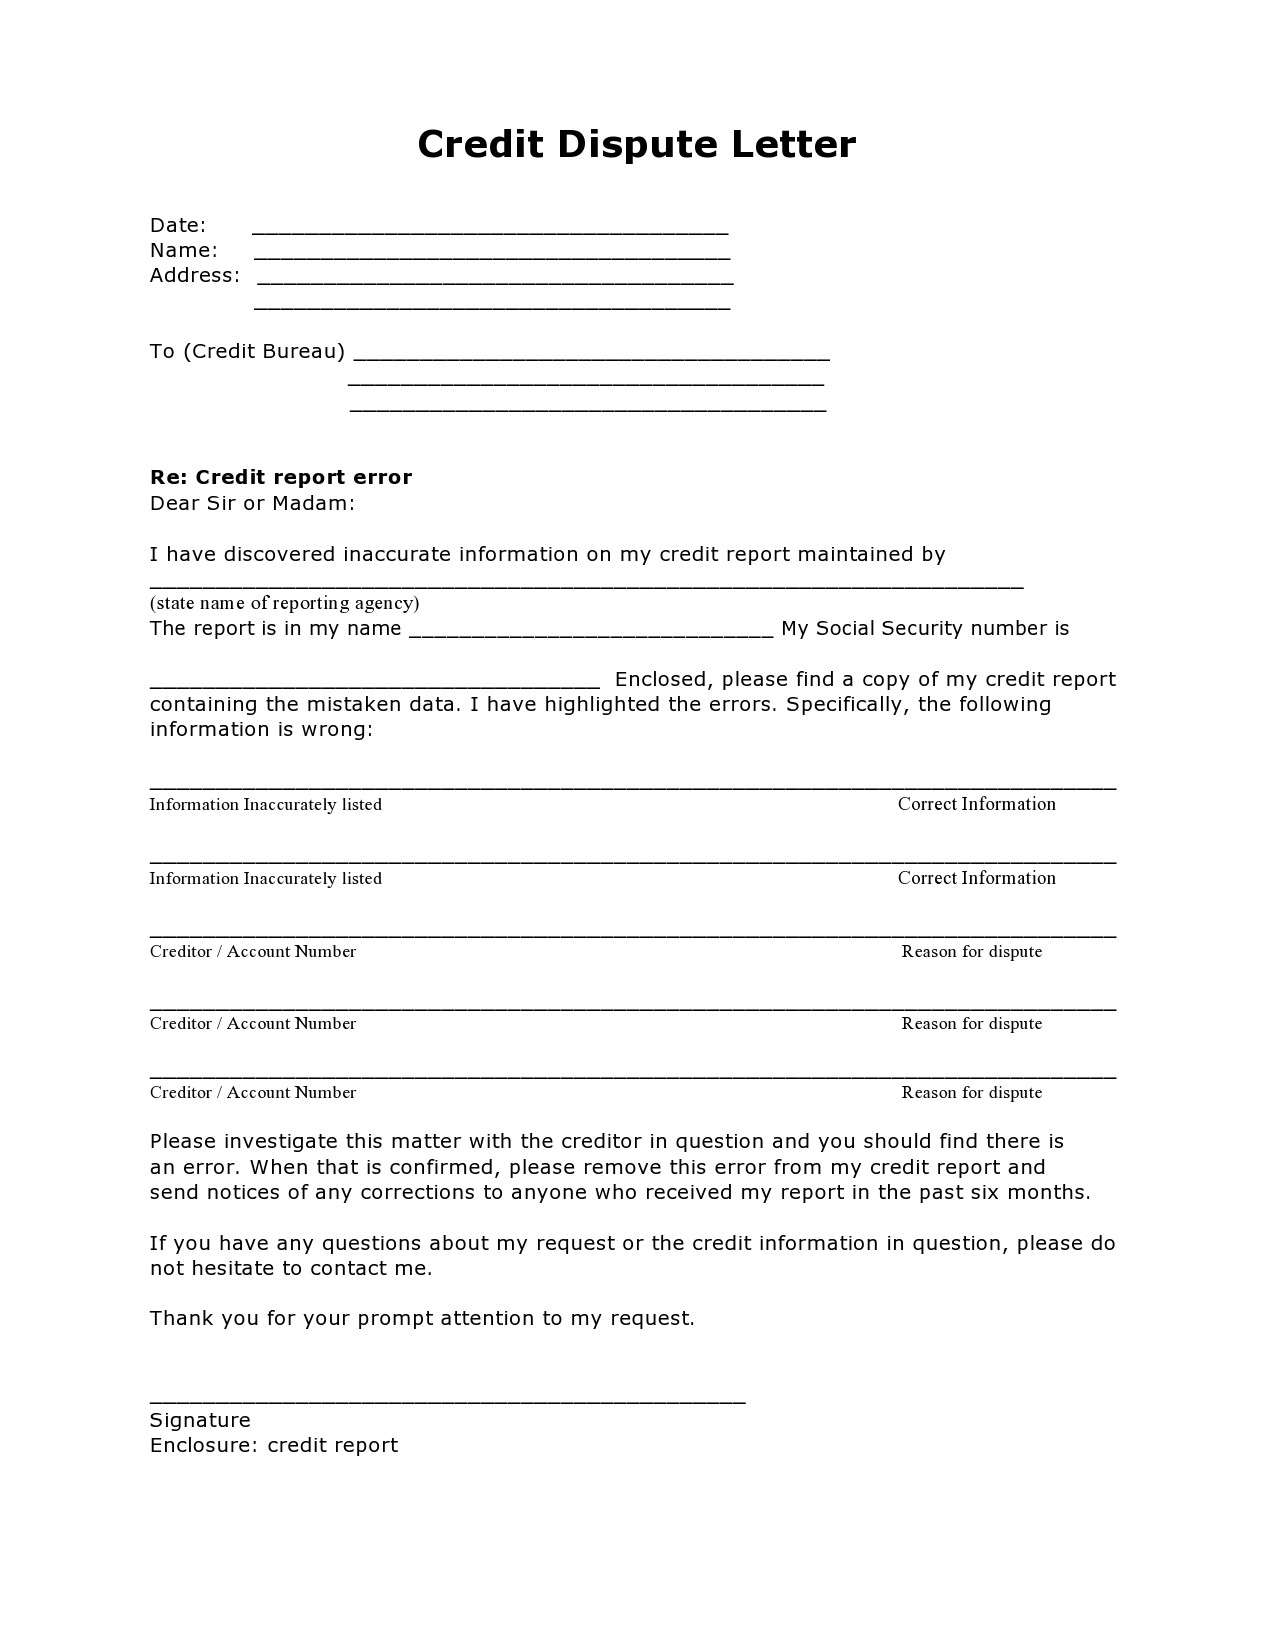
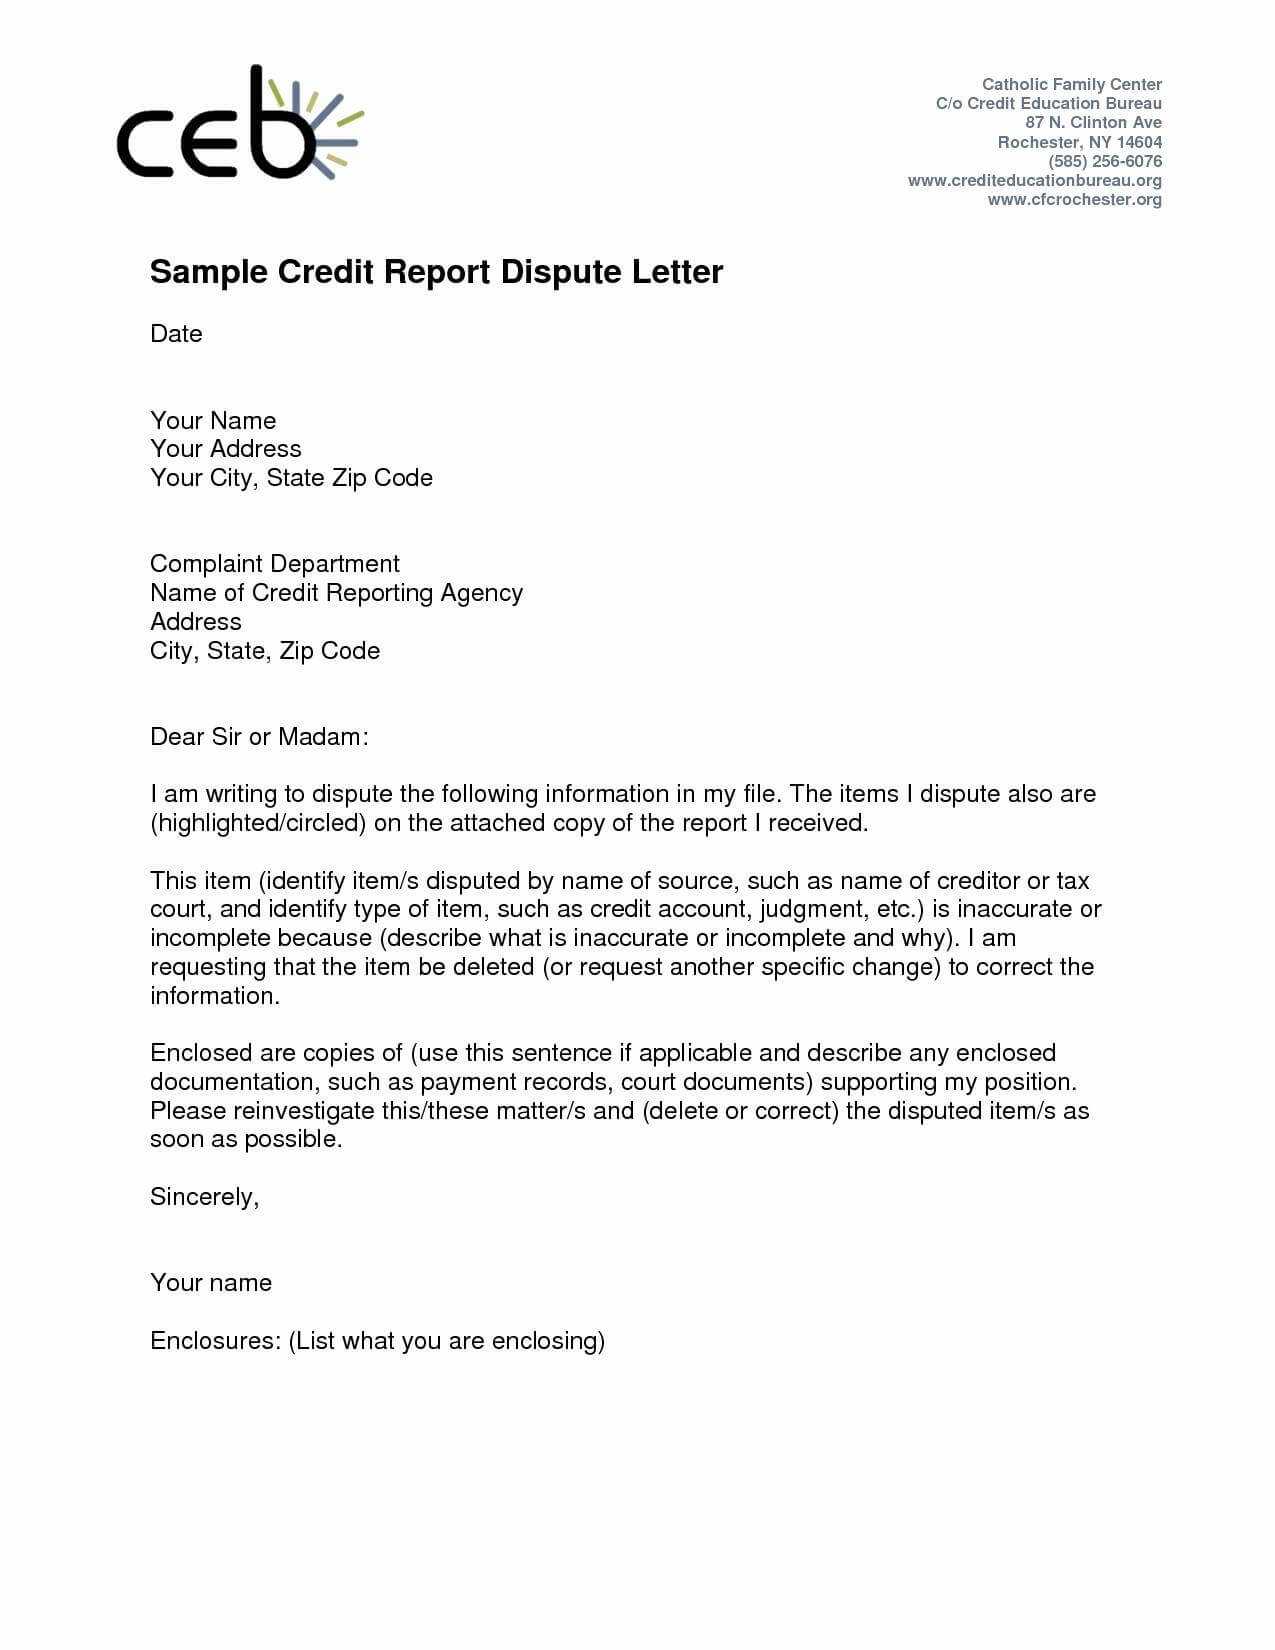
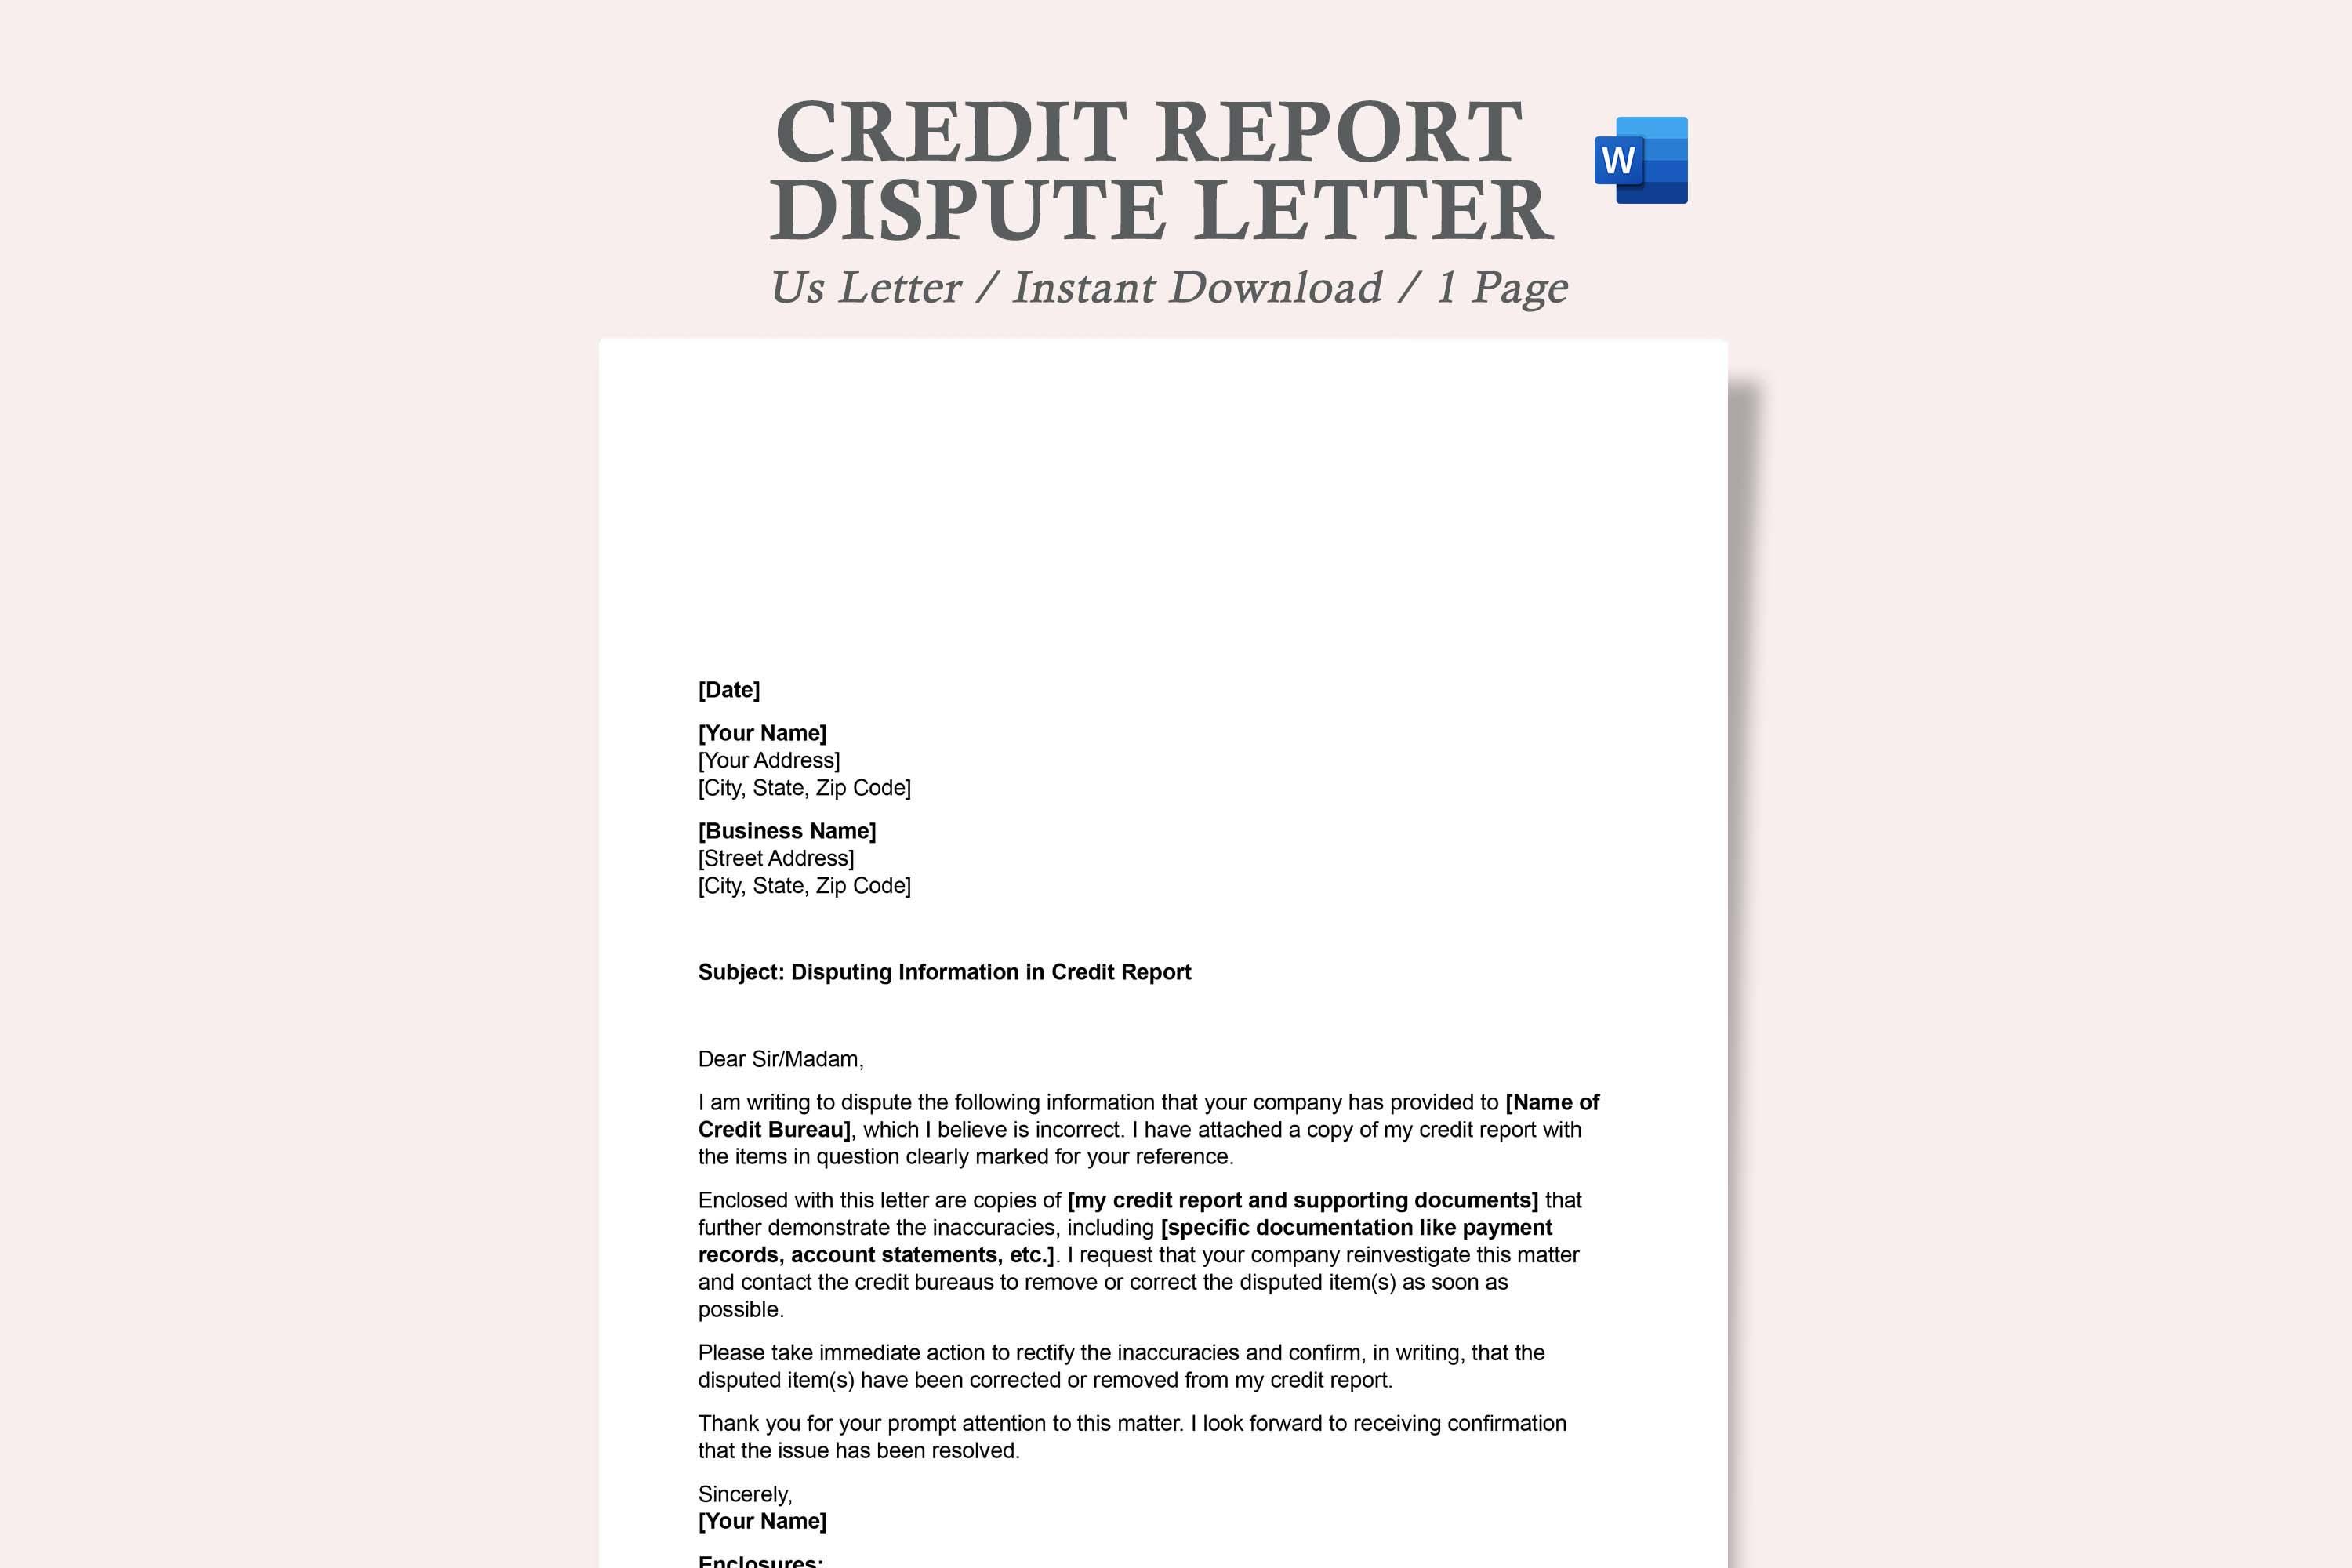
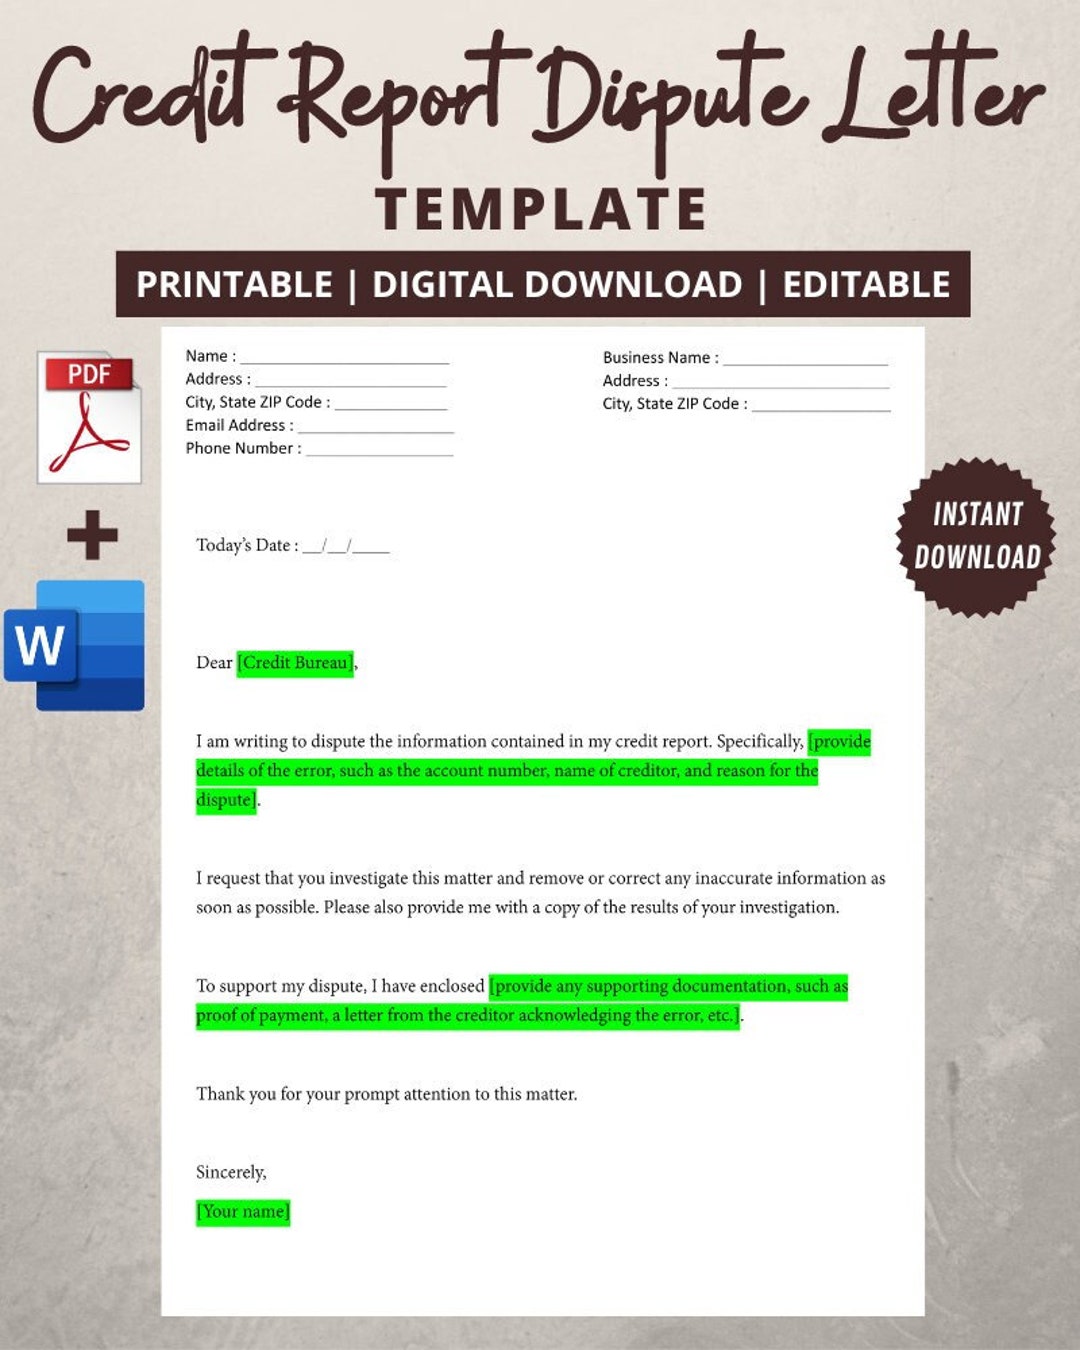
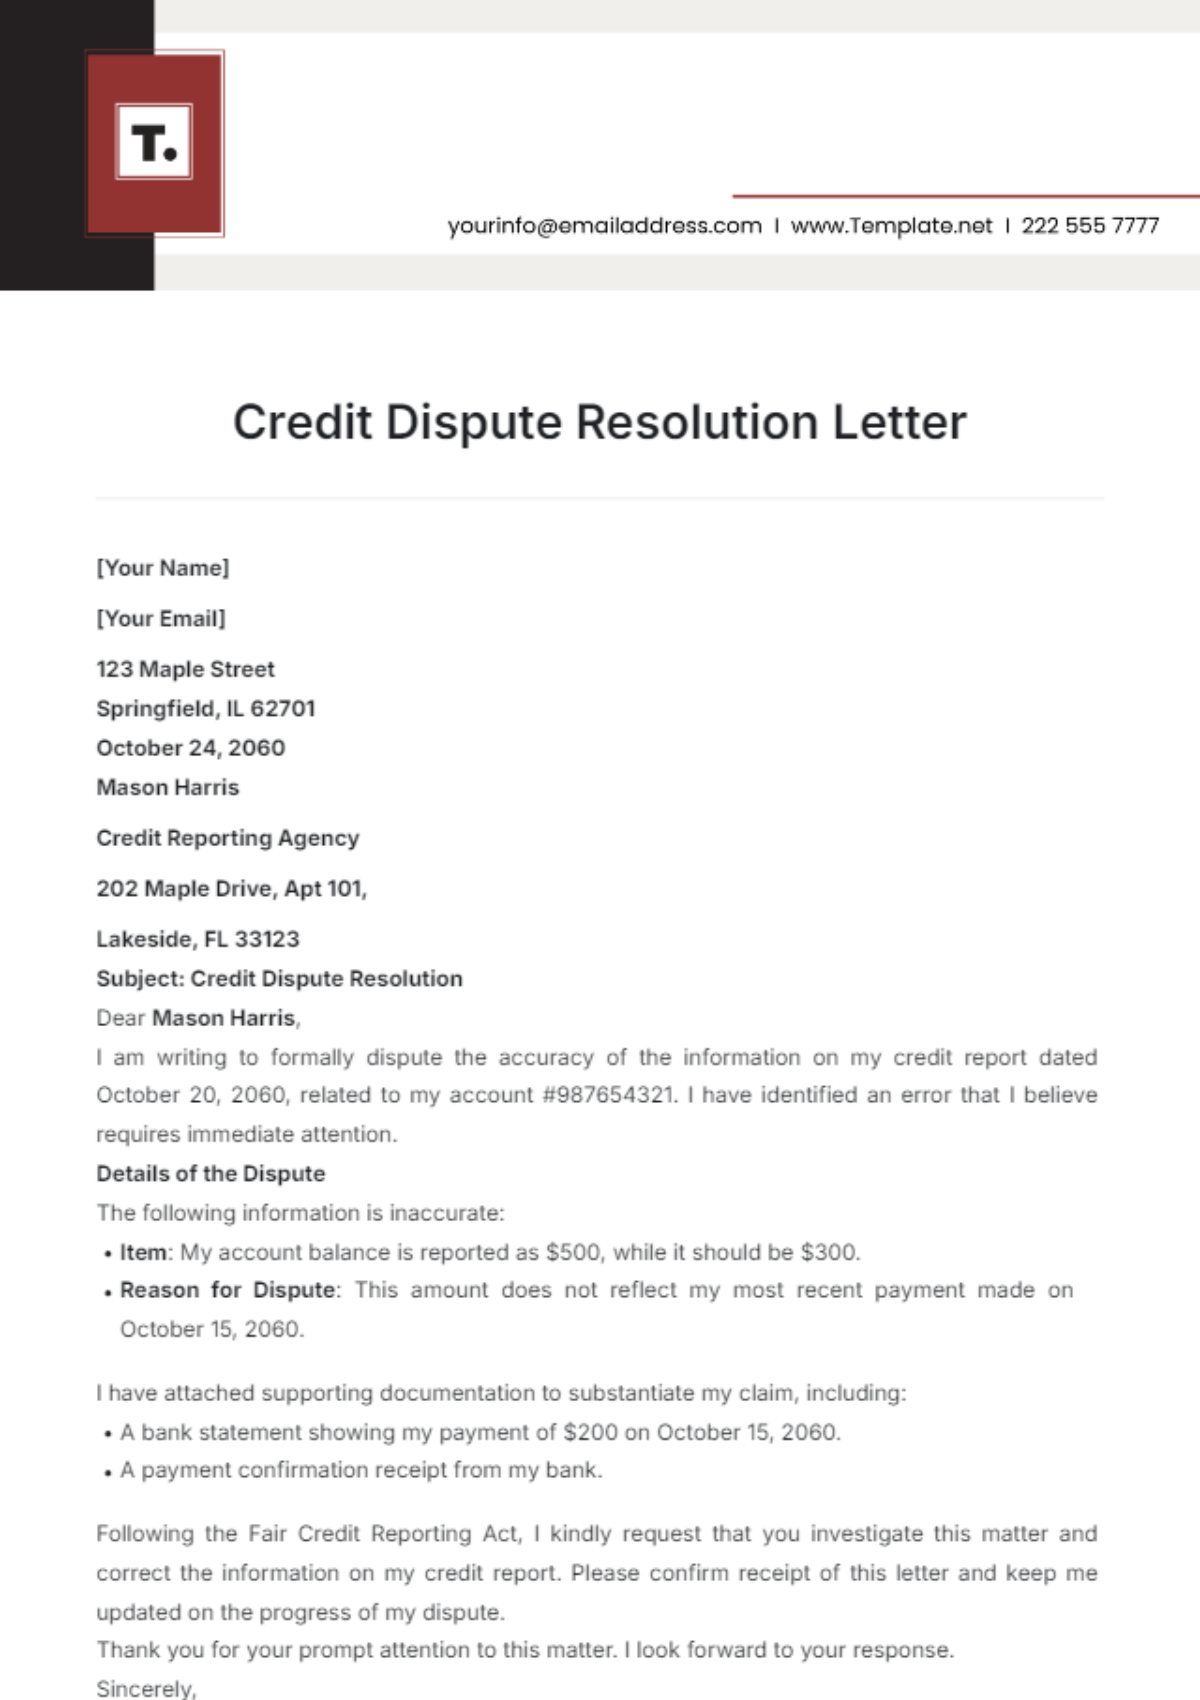
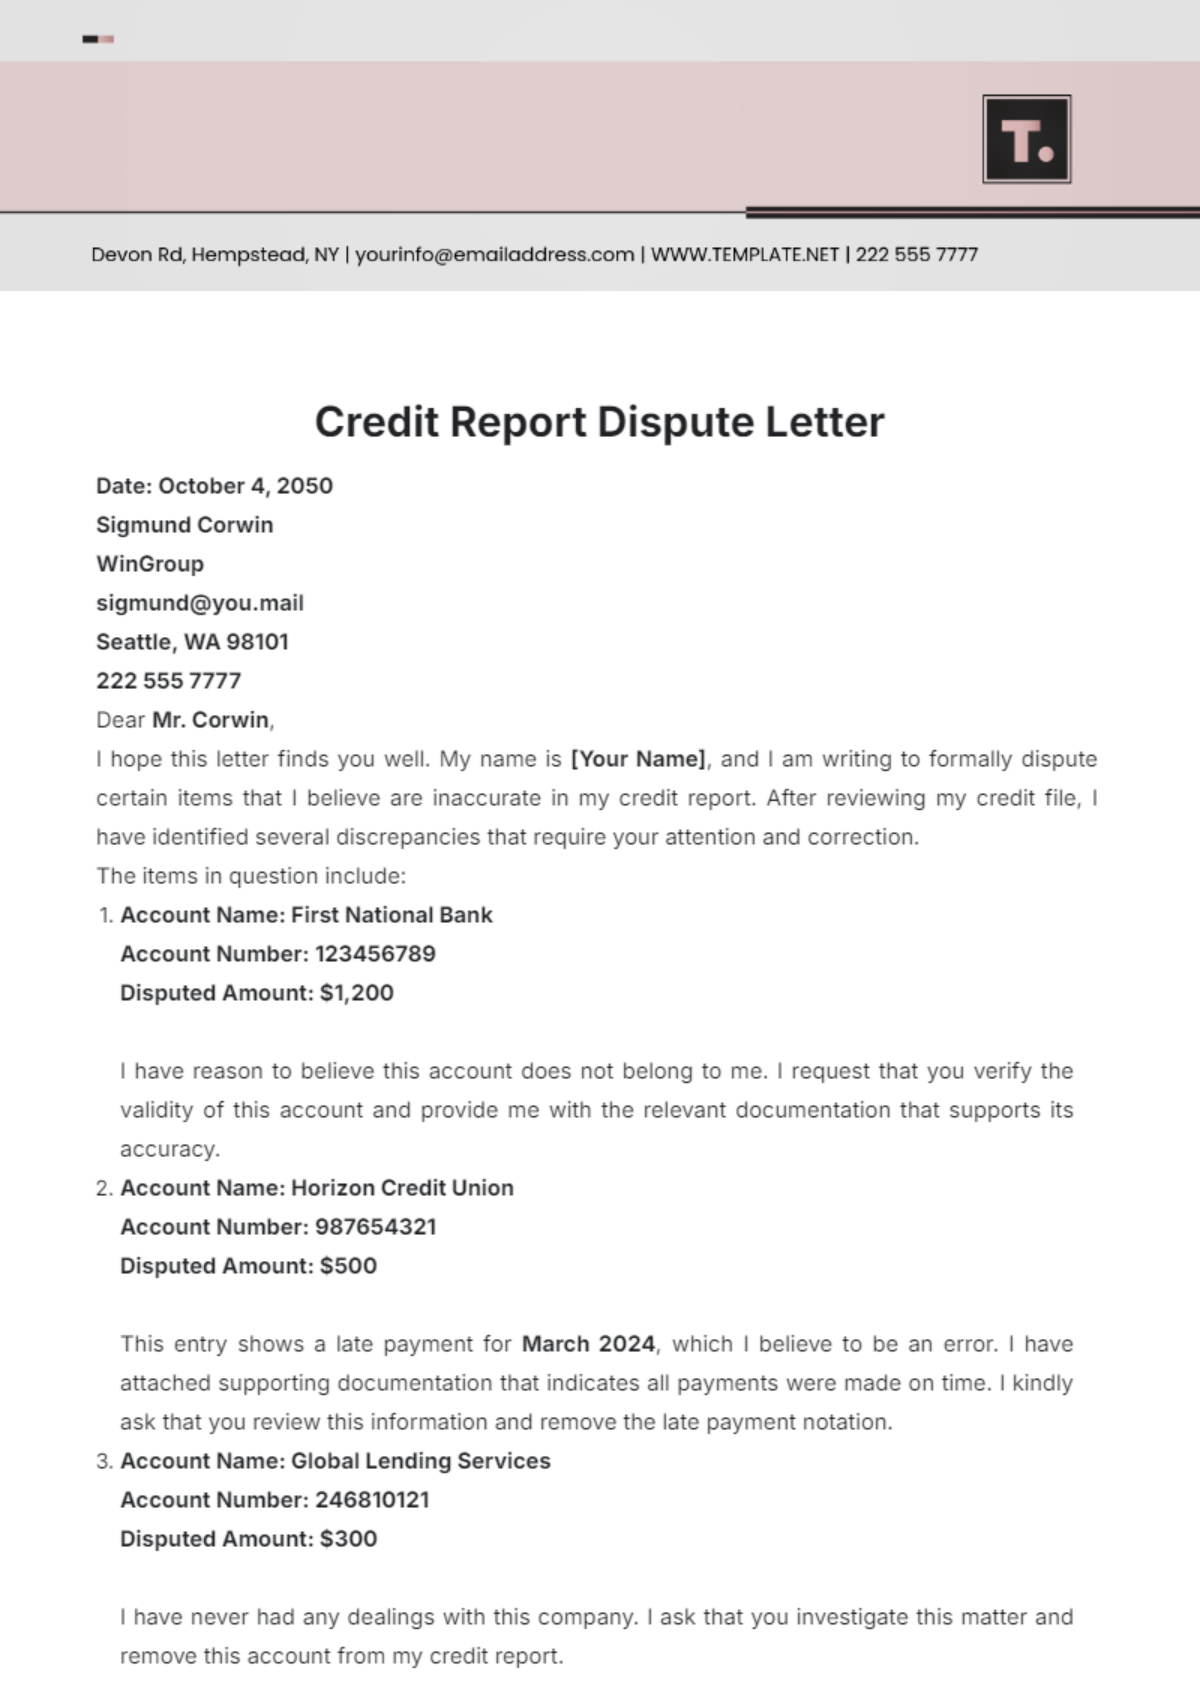
Below is a fully populated example that illustrates how each component works together. Replace the placeholders with your own details before sending.
[Your Full Name]
[Your Street Address]
[City, State ZIP Code]
[Phone Number]
[Email Address]

[Date]

Equifax Information Services LLC
P.O. Box 740256
Atlanta, GA 30374

Subject: Dispute of Inaccurate Information – Request for Investigation

To Whom It May Concern,

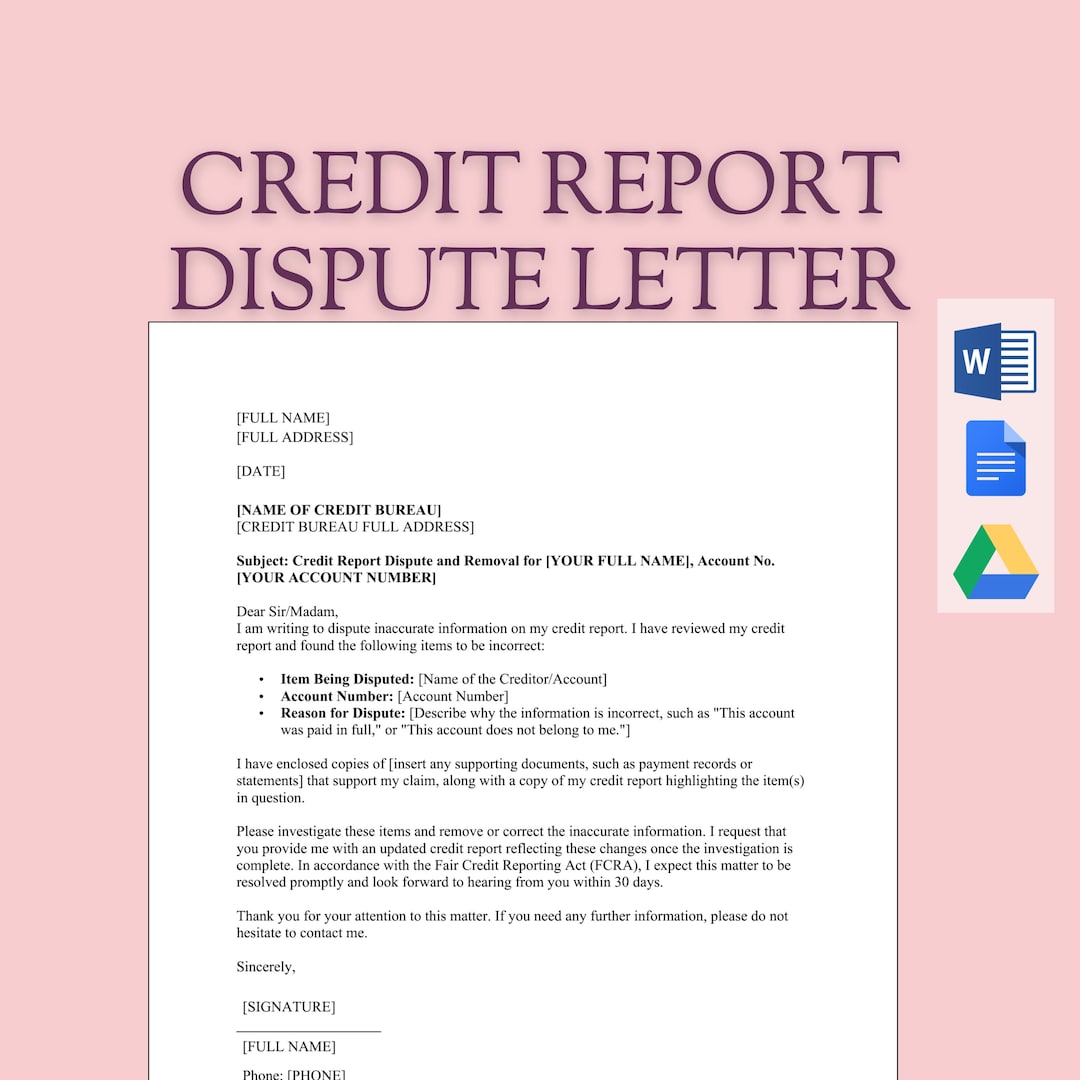
I am writing to dispute the following inaccurate information that appears on my Equifax credit report, identified by the reference number 123456789. Please investigate and correct these items in accordance with the Fair Credit Reporting Act.

1. Creditor: XYZ Bank
   Account Number: 987654321
   Disputed Item: Late payment reported on 04/15/2022 for $1,200.
   Reason for Dispute: This payment was made on 04/13/2022, as evidenced by the attached bank statement (Attachment A). The account status should reflect “Paid on time.”

2. Creditor: ABC Collections
   Account Number: 555666777
   Disputed Item: Charge‑off listed on 09/01/2021 for $350.
   Reason for Dispute: The debt was settled in full on 09/10/2021, and I have attached the settlement confirmation letter from the creditor (Attachment B). The charge‑off should be removed.

Please conduct a thorough investigation of the above items and delete the inaccurate entries from my credit file. I request a written confirmation of the results within the 30‑day statutory period. Enclosed are copies of the supporting documents mentioned above.

Thank you for your prompt attention to this matter.

Sincerely,

[Signature]
[Typed Name]
Common Mistakes to Avoid When Using a Template
- Leaving out the account number or creditor name, which makes it difficult for the bureau to locate the record.
- Submitting original documents instead of copies; originals can be lost and may be required later for verification.
- Using overly emotional language or threats; a respectful tone is more effective and aligns with cultural expectations of professionalism.
- Failing to keep a copy of the sent letter and all attachments for personal records.
- Neglecting to send the letter via a traceable method, which could result in the bureau claiming non‑receipt.
Frequently Asked Questions
How long does the investigation process take?
Under the FCRA, credit bureaus must complete the investigation within 30 days of receipt. If they need additional information, they may extend the period by up to 15 days, but they must notify you of any extension.
Can I dispute multiple items in one letter?
Yes. List each item separately, number them, and attach corresponding evidence for each. This approach streamlines the process and reduces the number of letters you need to send.
What if the bureau refuses to correct the error?
If the bureau concludes the information is accurate, they must provide you with a copy of the verification source. You can then contact the original creditor directly, request a re‑investigation, or file a complaint with the Consumer Financial Protection Bureau (CFPB).
Do I need to update my credit report after the dispute is resolved?
Once the bureau updates the record, they will send you a free copy of the revised credit report. Review it promptly to ensure the correction appears as expected.
Final Thoughts – Crafting a Winning Dispute Letter
In the spirit of Asian meticulousness, treating your credit report dispute as a formal, respectful correspondence can dramatically improve the odds of a favorable outcome. By employing a structured Credit Report Dispute Letter Template, attaching clear evidence, and following the procedural steps outlined above, you demonstrate both diligence and courtesy—qualities that resonate deeply with lenders and credit bureaus alike. Remember, the ultimate goal is not just to erase a single error, but to preserve the integrity of your financial reputation for years to come. Take a moment today to review your report, personalize the template, and send that letter; the peace of mind that follows is well worth the effort.


Related posts of "Credit Report Dispute Letter Template"
